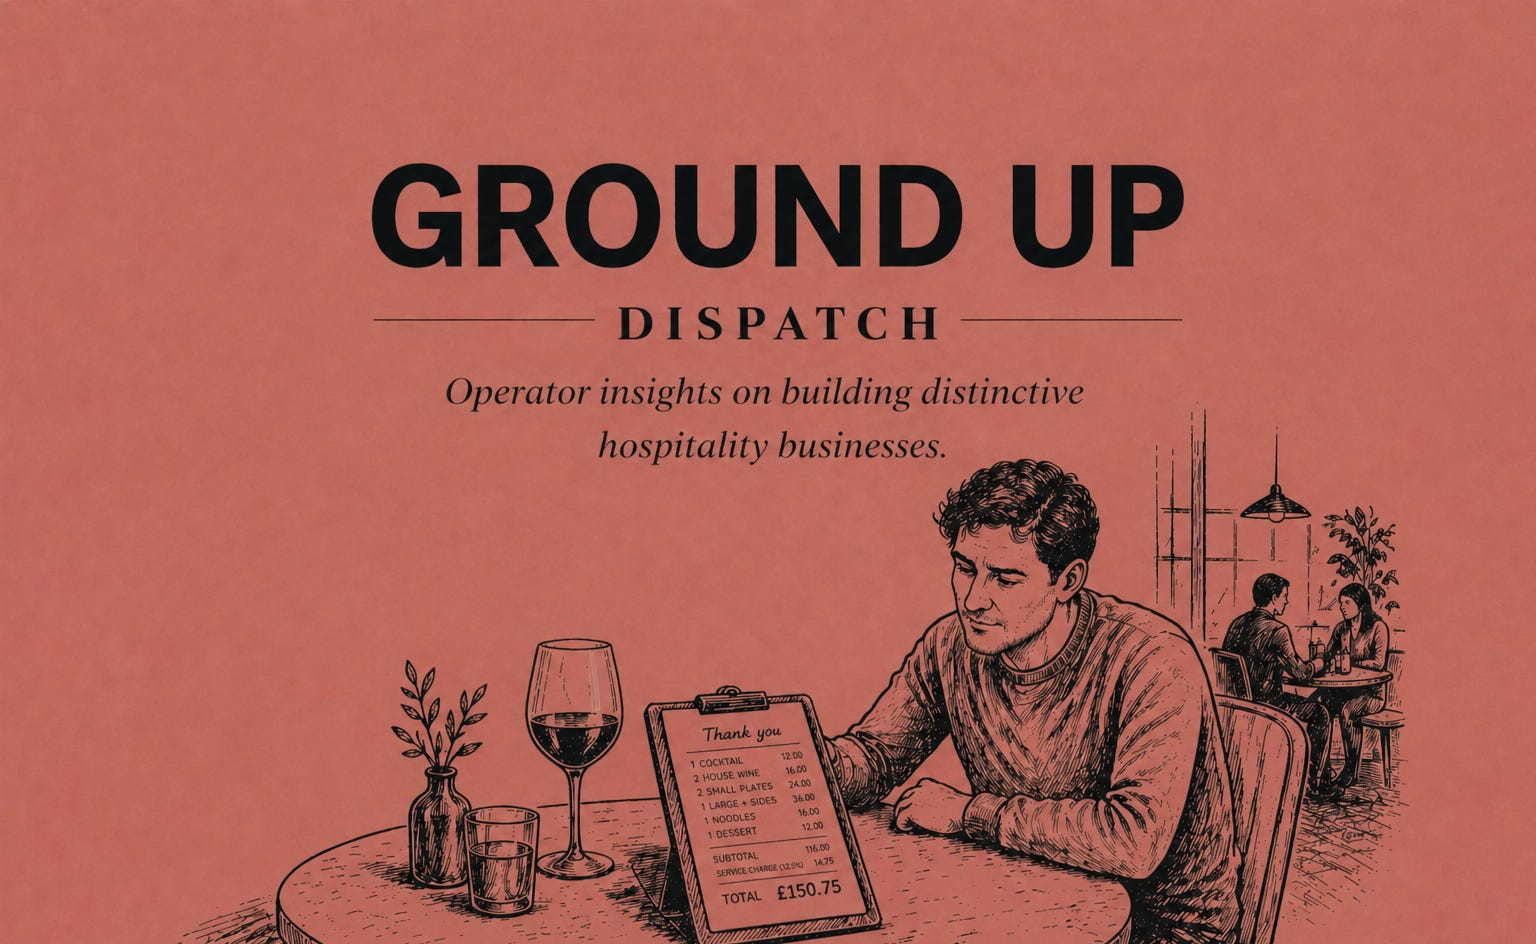
Not so long ago I genuinely shocked myself handing out a bill. Two guests - one cocktail each, a couple of glasses of house wine, two small plates, two large, a couple of sides and one shared dessert. North of £150 including service charge.
I stood there for a moment and thought: is that really what it costs to casually dine out now? Where have the days of £30 a head gone?
18 months on, looking at the same bill with fresh eyes, I’d say it was fair value for the quality on offer. That’s not a defence of high prices but the uncomfortable truth about where the UK, and particularly the London market has landed. It’s the new norm, it isn’t going to reverse, and understanding why requires looking at what’s happened to the economics of running a restaurant over the last four years.
The Numbers and What Drove Them
That same bill in 2019 would have been around £100 - a rise of around 50% in under a decade. UK food prices overall rose by under 10% in the entire decade before 2022, then by 25% between January 2022 and January 2024 alone, peaking at 19.1% annual inflation in March 2023, the highest rate since 1977. Food prices are still roughly a third higher than five years ago, despite inflation cooling - and that figure isn’t abstract, it’s in every supplier invoice, every menu reprint and every awkward conversation with a regular who remembers what things used to cost.
The turning point was spring 2022. Lockdown restrictions lifted, demand came flooding back - and then the economics hit. Brexit had already begun to reshape supply chains but this was when the cost became unavoidable. The UK imports around 40% of its food, much of it from the EU, and what had been frictionless was now anything but. Border checks, paperwork, delays - all of it added cost to products with a shelf life of days. A box of peppers that once cost £5 were being delivered to London kitchens closer to £12. From April 2024, further border checks added a common user charge of up to £145 per consignment - those costs don’t sit in isolation, they move through the chain and land on the plate.
Then Putin invaded Ukraine. Energy costs surged. Everything depended on contract timing - lock in early and you could manage it, renew later as volatility peaked and bills jumped 20-40% against pre-war levels. For some operators, particularly those with multiple sites and less flexibility, that was enough to tip them over the edge.
Labour costs followed the same relentless trajectory. The National Living Wage has risen by around 40% since 2020, hitting £12.21 per hour in April 2025 and rising again to £12.71 in April 2026. UK Hospitality estimates wage increases alone represent a further £1.4 billion in additional cost for the sector annually and for an industry that pays its staff largely minimum wage plus service charge – this has a significant impact. April 2025 also brought an increase in employer national insurance contributions - from 13.8% to 15% - combined with a reduction in the NI threshold from £9,100 to £5,000. What made this particularly damaging wasn’t the scale but the fact it was unforeseen. Wage rises can be planned for, an unannounced threshold change landing mid-year cannot.
Then the one counterbalance disappeared. Business rates relief, which had kept a significant number of operators alive through the pandemic and beyond, had been tapering off year on year but has now been fully withdrawn. From April 2026, restaurants are back on full rates - and in central London, particularly Westminster, those levels are quite plainly extortionate. For a medium-sized site, business rates alone can approach or exceed £100,000 a year.
The Service Charge Sting
October 2024 brought another hit - new legislation requiring service charge to be passed on to staff in full, removing the ability for businesses to retain any meaningful portion of it.
It’s worth being clear about what we’re talking about here. Cash tips left on the table or added by card at the discretion of the diner have always belonged to the staff - that’s straightforward and right. The complexity sits with the discretionary service charge that appears as a line on the bill, typically 12.5%, which has historically been managed differently by different operators.
Across much of the industry, a portion of that service charge had been retained by the business - not as pure profit in most cases, but to cover breakages, uniforms, staff events, or to support margins that were already tight. It wasn’t a perfect system and there were operators who abused it. A legitimate grievance. What it didn’t warrant from government was a blanket approach that treated the responsible and the exploitative in exactly the same way.
The impact was immediate - a restaurant taking £20,000 a month in service charge could lose £6,000-£8,000 of retained income overnight, with no transition and no offset. For many, that was the difference between a marginal profit and a loss. The secondary effect is a pay structure that no longer aligns with experience or responsibility - in busy central London sites, junior floor staff can now earn £15-£18 an hour or more, which compresses the gap between entry-level and senior roles and makes it harder to reward experience, retain leadership and build stable teams.
The result was predictable: another round of menu price increases. Not optional. Simply necessary.
Both Sides Squeezed - and Not Everyone Was Honest About It
What makes the current situation structurally different from previous periods of cost inflation is that both sides tightened simultaneously - and neither fully recovered. Operators faced soaring costs from every direction while the customers sitting across the table were facing their own squeeze - disposable income falling, the cost of living consuming an ever-larger share of household budgets - dining out shifting from routine to occasion. The spontaneous midweek dinner became a considered choice.
The perception of many is that restaurants got greedy - that price rises were opportunistic rather than necessary. The truth is more nuanced. In 2019, before Covid turned everything upside down, hospitality margins in a well-run operation were healthy. Operators who came through the pandemic into 2022 were rebuilding from a standing start - and the cost surge that followed left almost no room to absorb it. Most independent operators raised prices reluctantly, late, and by less than the cost increases they were absorbing.
But there were greedy operators out there too - raising more than the economics justified and skewing the public perception of the honest ones. The industry suffered for that and it’s worth naming it rather than pretending the price rises were universally defensible.
The honest version is this: the bill got bigger because the cost of producing the meal got bigger - not marginally, but through a sustained, multi-front increase that’s fundamentally reset what it costs to run a restaurant in the UK. For most operators, the rises were survival, not opportunism. But not for all.
Where the Market Is Now
The London market is too vast for sweeping generalisations, but it seems to me that the operators performing most consistently are those who have built their model around one excellent core offering - the ramen bar, the £15 steak and chips, the wood-fired pizza with six toppings. A focused menu simplifies the supply chain, tightens cost control and keeps prices genuinely accessible. In and out in under an hour, a couple of drinks, £25–30 a head. That’s where demand is most resilient right now.
The mid-market has had the hardest time - now too expensive to frequent, but not enough of a treat to justify a splurge. The squeeze has been most visible in this space, and the closures most frequent.
Food inflation has ticked back up through late 2025 and into 2026 after a brief period of easing. Wage costs continue to rise. Business rates remain punishing. The structural pressures that drove the price increases of the last four years haven’t gone away - they’ve settled in.
The £30 dinner, as it was, isn’t coming back. The question now is whether the industry can find a sustainable equilibrium at the new price point, or whether the gap between what things cost and what people can afford to pay continues to widen.
From where I’m standing, that gap is still widening.
Ground Up Dispatch
Operator insights on building distinctive hospitality businesses. Written by Dan Anton.
Subscribe hello@groundupprojects.co.uk
Work with Ground Up Projects
Ground Up Projects works with founder-led restaurants on the commercial and operational decisions that determine whether a good concept becomes a viable, sustainable business. Our services · Get in touch